Medical Necessity: When Is Relationship Counseling Insurance Covered?
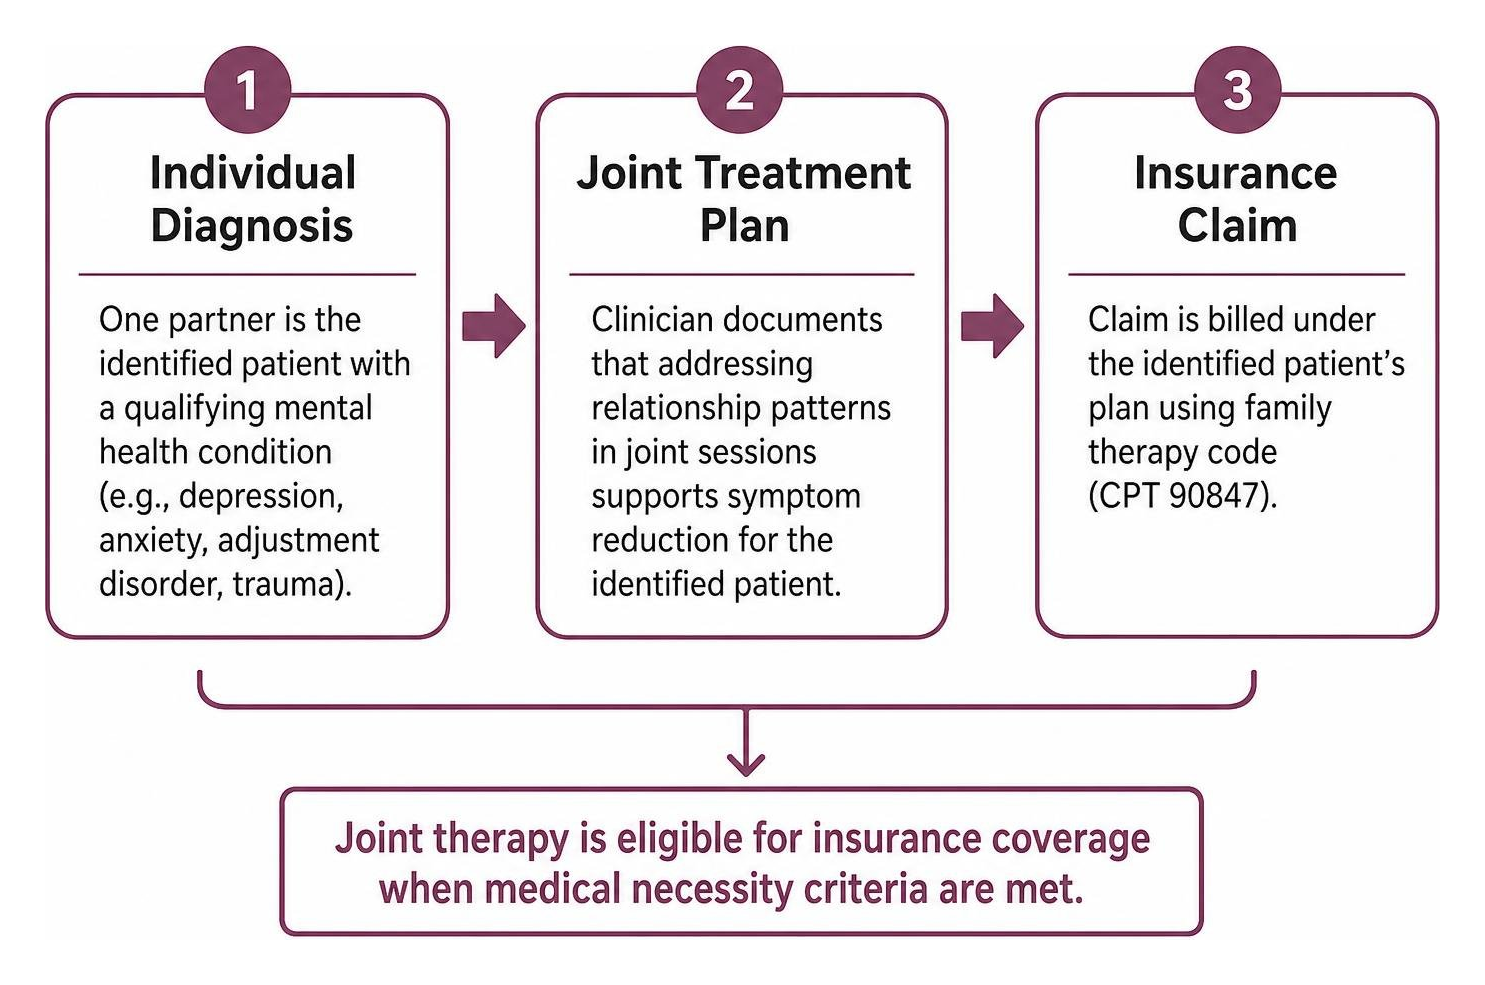
Relationship counseling insurance covered sessions are usually possible only when therapy is medically necessary for one partner’s diagnosed mental health condition. In most cases, the claim is billed under the identified patient’s benefits, uses a family psychotherapy code, and must show how joint sessions support treatment goals. Sessions focused only on general relationship enrichment, communication practice, or premarital preparation are typically private pay rather than health insurance benefits.
Understanding how insurance plans handle couples sessions requires looking closely at how health plans define medical care. For any commercial or public health plan to reimburse a service, the treatment must meet standard criteria for medical necessity. According to clinical coverage guides published by LegalClarity, insurers view medical necessity as treatment designed to evaluate, diagnose, or manage an identified mental health condition listed in diagnostic manuals like the DSM or ICD.
When partners seek therapy purely to resolve household arguments or enhance overall closeness, insurers classify those goals as relational enhancement rather than healthcare. Relational distress without an underlying condition receives administrative billing codes known as Z codes, such as code Z63.0 for relationship distress with a spouse or partner. Health insurers almost universally exclude standalone Z codes from reimbursement because they describe life circumstances rather than clinical health conditions.
Therapy involving both partners becomes eligible for coverage when one person experiences a qualifying condition, such as depression, generalized anxiety, adjustment disorders, or trauma. In these circumstances, relationship patterns frequently intersect with symptom management. When a clinician determines that addressing family dynamics directly supports symptom reduction, joint sessions satisfy the requirement for medical necessity. Learning what mental health services are actually covered helps partners set realistic expectations before their first visit.
Designating an Identified Patient to Get Relationship Counseling Insurance Covered
Insurance claims systems are structured around individual beneficiaries rather than couples as a single unit. To have relationship counseling insurance covered, one partner must be designated on paperwork as the identified patient.
The identified patient is the individual who holds the qualifying diagnosis and whose medical record houses the clinical treatment plan. The therapist structures documentation around how joint interactions alleviate the identified patient’s symptoms. This designation functions primarily as an administrative tool for insurance processing and does not mean one partner is at fault for relational friction.
Couples selecting who will serve as the identified patient often consider clinical symptom severity, plan benefit design, and personal preference. Professional care through structured Couples Therapy ensures both individuals receive thoughtful attention while administrative requirements remain fully compliant.
Marriage Counseling vs. Family Psychotherapy Billing Codes
The terminology used on insurance claims determines whether a claim is processed smoothly or rejected. Billing guidance from The Insurance Maze highlights that standard commercial claims rely on specific Current Procedural Terminology codes established for family therapy:
- CPT Code 90847: Family or couples psychotherapy with the identified patient present, generally used for a standard family therapy session.
- CPT Code 90846: Family or couples psychotherapy without the identified patient present, used when consulting a partner to support the primary treatment plan.
- CPT Code 90837: Individual psychotherapy, which cannot be used for ongoing couples sessions.
Therapists must maintain accurate coding. Attempting to bill ongoing joint therapy under individual psychotherapy codes to secure different reimbursement rates violates billing guidelines and can trigger claim audits. Accurate claims use code 90847 alongside the identified patient’s primary diagnosis code.
Navigating Network Benefits, Plan Rules, and Out of Pocket Costs
The financial framework of insured relationship counseling depends on your plan network status, deductible status, and cost sharing requirements. When you understand your coverage details, you can plan your care without unexpected administrative surprises.
| Coverage Type | Typical Cost Structure | Diagnostic Requirement | Claim Process |
|---|---|---|---|
| In Network Plan | Fixed copay or standard coinsurance | Requires qualifying diagnosis and identified patient | Submitted directly by provider |
| Out of Network Plan | Reimburses a percentage of allowed amount after deductible | Requires qualifying diagnosis and identified patient | Submitted via superbill by client |
| Self Pay Arrangement | Full session rate set by practice | No diagnosis or medical records required | Paid directly at time of service |
Understanding what services your policy covers gives clarity on how deductibles and coinsurance interact throughout the benefit year.
How Health Plans Review Family Psychotherapy Claims
Health plans often process behavioral health claims through dedicated administrative networks. While each plan manages its own provider directory, mental health benefits are generally expected to be handled consistently with other medical benefits.
Under these standards, plans may reimburse CPT code 90847 when documentation shows that relational interventions directly treat the identified patient’s diagnosed condition. Specialized modalities such as the Gottman Method or Emotionally Focused Therapy do not have separate billing codes. They are billed under standard family psychotherapy codes. Checking your specific couples therapy insurance parameters helps verify network participation and preauthorization rules.
Virtual Sessions and Telehealth Parity Rules
Virtual care has expanded access to relational support for busy couples. Most commercial insurance plans provide equal coverage for telehealth sessions under standard behavioral health benefits.
To ensure claims for virtual sessions are processed properly, providers include specific billing details:
- Place of Service Code 10: Indicates telehealth services delivered while the client is located in their personal residence.
- Place of Service Code 02: Indicates telehealth services delivered when the client is at an offsite location outside their residence.
- Telehealth Modifiers: Appended to CPT code 90847 to show the session was held via a secure, two way audio and visual connection.
Clinicians must be licensed in the state where the clients are physically located during the virtual appointment. Utilizing secure Couples Therapy Online allows partners to work together from the comfort of home while using their telehealth benefits.
Alternative Payment Methods and Low Cost Options
When insurance coverage is not applicable because sessions focus strictly on marital enrichment, several reliable funding alternatives exist. These options help couples invest in their relationship without needing a clinical diagnosis on their medical record.
Exploring practical tips for managing therapy costs helps couples find an approach that matches their financial comfort level.
Utilizing EAPs, HSAs, and FSAs
Many employers offer Employee Assistance Programs that may provide a limited number of short term counseling sessions per life event at no out of pocket cost to the employee. EAP benefits generally do not require a mental health diagnosis, making them well suited for early conflict resolution or communication tune ups.
Tax advantaged healthcare accounts can also offset therapy expenses:
- Health Savings Accounts: Paired with high deductible health plans, allowing pre tax contributions to pay for eligible medical expenses.
- Flexible Spending Accounts: Employer established accounts allowing pre tax funds to cover healthcare services during the plan year.
Under official tax guidelines, funds from these accounts can cover therapy sessions when the care is tied to a diagnosed health condition. Some plan administrators may request a Letter of Medical Necessity from your provider. Investing in relationship health helps rebuild trust and connection while keeping finances manageable.
Out of Network Superbills and Sliding Scale Therapy
If your preferred therapist does not contract directly with your insurance network, you can still utilize out of network benefits if your plan includes PPO coverage. In this arrangement, you pay the therapist directly and submit an itemized document known as a superbill to your insurer.
A standard superbill includes essential billing details:
- Provider National Provider Identifier and Tax Identification Number.
- CPT billing code 90847 along with the relevant clinical diagnostic code.
- Date of service, total fee paid, and clinical licensing credentials.
Your insurer processes the superbill against your out of network deductible and sends reimbursement according to your policy terms. If out of network reimbursement is not an option, many providers offer sliding scale rates or community clinic placements. It is quite common for experienced therapists to operate without insurance contracts, giving clients flexibility over their treatment goals.
Step by Step Guide to Verifying Benefits and Appealing Denials
Verifying your behavioral health benefits before your first appointment prevents billing confusion and ensures you understand your financial responsibilities. Taking a structured approach simplifies the entire process.
Reviewing your general insurance coverage pathways before calling customer service gives you confidence during the conversation.
Verifying If Your Specific Relationship Counseling Insurance Covered Claim Is Eligible
When calling your insurance carrier, avoid asking broad questions like “Is marriage counseling covered?” because representatives may default to denying non medical relational enrichment. Instead, use specific terminology:
- State that you want to check your outpatient behavioral health benefits.
- Ask if CPT code 90847 is covered when paired with a primary mental health diagnosis.
- Confirm whether your plan requires prior authorization before your initial visit.
- Verify your individual and family deductible amounts and check whether they have been met.
- Inquire about your exact copay or coinsurance amount per session.
- Ask if telehealth services under CPT code 90847 carry equal coverage to in person appointments.
- Record the date of the call, representative name, and reference number for your records.
Connecting with resources that explain how to locate providers in your network makes the onboarding process seamless.
How to Appeal a Denied Couples Therapy Claim
If an insurance claim for couples therapy is denied, you have the right to request a formal review. Claim denials often result from clerical oversights, missing diagnostic codes, or incorrect network IDs rather than an absolute lack of coverage.
Steps to appeal an adverse benefit determination:
- Review the Explanation of Benefits: Identify the exact denial code listed on the statement.
- Request a Provider Peer to Peer Review: Your clinician can speak with a medical reviewer to explain how joint sessions support symptom reduction.
- Submit an Internal Appeal: File a formal written appeal within the deadline listed in your plan documents, including a letter of medical necessity from your clinician.
- Reference Parity Protections: Cite federal mental health parity standards if mental health family therapy is restricted more heavily than physical medical consultations.
- Request an External Independent Review: If internal appeals are upheld, request an external review through your state insurance board, which produces a binding decision for the insurer.
Comprehensive guides on finding licensed mental health specialists offer additional support for managing administrative hurdles.
Frequently Asked Questions About Relationship Counseling and Insurance
Can both partners bill their separate insurance plans for the same couples therapy session?
No. Submitting claims to two separate insurance carriers for the same joint therapy session is prohibited by billing regulations. A single therapy session can only be billed to one primary insurance policy under the designated identified patient. Submitting two claims for the same appointment creates duplicate billing.
Does insurance cover premarital counseling or marriage enrichment?
Health insurance does not cover premarital counseling or general relationship enrichment. These services focus on relationship development, communication education, and future planning rather than treating a diagnosable medical condition. Specialized Couples Therapy Pre Marital programs are arranged as private pay services.
What should we do if our therapist does not accept health insurance?
If your therapist does not accept insurance directly, you can pay for sessions out of pocket and request a monthly superbill. You can then submit this document to your insurance company for potential out of network reimbursement. Discussing what happens during sessions during an initial consultation helps ensure the therapeutic approach aligns with your goals.
Conclusion
Navigating health insurance for relationship support does not have to be overwhelming. When mental health challenges affect your shared life, health insurance can serve as a valuable resource to make professional care accessible and sustainable. By understanding medical necessity criteria, utilizing proper family psychotherapy billing codes, and checking your specific plan details, you and your partner can access high quality care with confidence.
At Collective Counseling Solutions, we simplify the journey by connecting you with skilled, licensed therapists who accept insurance for both in person and virtual care. Relational wellness is a meaningful investment in your future. Reach out today to explore our dedicated Couples Therapy services and start your path toward lasting connection.